Reading A Billing Statement
A bill is a dated record of what a seller says you owe for a defined period. Its total may blend a recurring price, measured use, government charges, prior activity, and adjustments. A $96 statement can therefore contain only $70 for the current service. The rest may be tax, a one-time fee, or an unpaid $12 carried from last month. Check the dates. Start with the statement date, account number, billing period, amount due, and due date. Those five fields anchor every later comparison.
Do not treat the payment screen as the bill. A screen may show a rounded total or a balance after a pending payment, while the statement shows the charge dates and calculation labels. Federal law in the United States gives credit-card users billing-error protections for certain disputes, but written notice generally must reach the issuer within 60 days after the first statement showing the error. Timing matters.
Read from top to bottom once without doing math. On a second pass, mark every line that changed from the previous period. A charge is easier to explain when you know its start date, rate, quantity, and rule. A missing credit deserves the same attention as a new fee. Labels help.
Where Charges Hide
The headline total often conceals four different categories: recurring charges, variable charges, fees, and balance activity. A recurring charge stays stable until the agreement changes. A variable charge follows a meter, minutes, units, transactions, or another measure. Fees may arise from a late payment, paper statement, activation, transfer, or payment method. Categories differ. Balance activity includes old debt, credits, refunds, and interest.
Periods rarely line up neatly. A service may bill from the 12th through the 11th, while a bank payment posts on the 14th. A new plan can create a prorated line for 19 days plus a full upcoming month. That pairing looks like double billing, which, frankly, is why many disputes begin, yet the dates can show two different periods. Read 2 dates. Compare 2 billing periods side by side. A 31-day cycle can cost more than a 28-day cycle at the same daily rate. Pause there.
Taxes and surcharges create another source of confusion. Sales tax usually follows a taxable subtotal, while a regulatory or local charge may use a different base. In the United States, a credit-card statement can also show interest calculated from an annual percentage rate, or APR, divided across daily balances. Check the rate, the balance subject to interest, and the number of days. Check labels. Small labels matter.
Authorization holds are not always final charges. Hotels, fuel stations, and rental firms may place a temporary hold that changes available credit before the final amount posts. A $150 hold and an $82 completed charge can coexist briefly. Compare the status and posting date before claiming a duplicate. Status matters.
Steps To Audit A Bill
Match The Billing Period
Write the start and end date beside the statement total. Then compare that interval with the prior bill and any order confirmation. If a plan began on March 18, a first bill may contain a partial March charge and an April charge paid in advance. Dates decide. That pattern is common in recurring agreements. The contract or signup receipt should name the cycle.
Rebuild The Subtotal
Add the recurring price, each usage line, and one-time amounts before taxes. Use a calculator rather than mental arithmetic; a 1-cent rounding difference may appear when several rates are calculated separately. If the pre-tax sum differs, identify the first line that does not fit. Check twice. Save a screenshot of the itemized view, including the date shown in the browser.
Compare Units And Rates
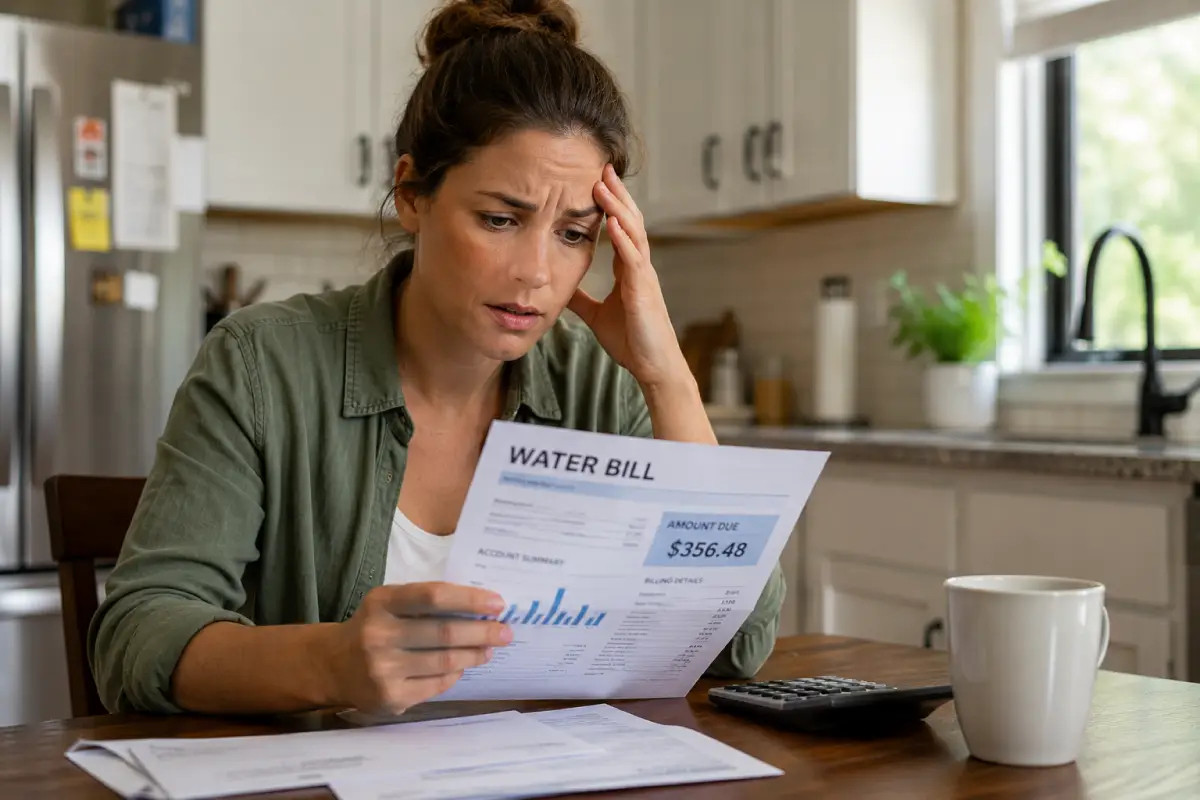
For metered charges, compare both the unit count and the price per unit. A utility-style bill may list 340 units this month and 290 last month, while a data plan may list 8.4 GB above its included amount. A higher total can come from more use, a new rate, or both. Compare both. The quantity and rate answer different questions.
Trace Every Fee
Find the fee name in the agreement, rate card, or account notices. A $5 processing fee may be disclosed only for a certain payment channel; a $25 late fee may depend on a missed deadline. Note the event that supposedly triggered it. Names count. Vague labels such as “service fee” call for a written explanation and the clause used. Write it down.
Check Credits And Payments
List every payment, refund, promotion, and adjustment separately. A payment made at 11:58 p.m. on a due date may post the next business day, depending on the stated cutoff and time zone. In one routine detail, account portals sometimes show “received” before the ledger says “posted.” Save both. Credits can expire or apply over 2 billing cycles, so read their terms. Logs help.
Build A Dispute Record
Make a short record with the disputed amount, statement date, transaction date, reason, and requested correction. Attach the receipt, prior statement, and a dated screenshot. File records. Use a 2-column note for dates and amounts. State facts before conclusions: “The bill lists 2 activation fees; the order confirmation lists 1.” That format gives the reviewer something concrete to check. Calls are useful, but follow up in writing. Be exact.
Two Billing Scenarios
In the first scenario, an account holder sees a $118 bill after changing a monthly plan on April 22. The invoice lists $18 for April 22–30, $80 for May, and $20 in local charges. The person expected $80 because the confirmation email highlighted the monthly price. Dates settle it. A date-by-date review shows a partial first period plus the next full period, not two May charges.
In the second, a shopper sees two $64 card entries from the same store on May 6. One entry says pending and the other says posted. The receipt shows a single $64 purchase. Watch status. Mark 2 entries when they share a date. Waiting 3 days may resolve a duplicate authorization, but the shopper should record both identifiers and contact the card issuer if both settle. The status changes the next step. Wait briefly.
The table below separates a charge that needs evidence from one that needs time. It is a screening tool, not a substitute for the agreement. Review it with the matching receipts and notices. Use records. Keep 2 screenshots: one before and one after posting.
| Signal | First Check | Useful Record | Next Move |
|---|---|---|---|
| New fee | Trigger and rate | Terms and notice | Request the clause |
| Higher usage | Units and rate | Prior statement | Compare the period |
| Duplicate entry | Pending or posted | Receipt and identifiers | Monitor or dispute |
Errors That Cost Money
A common mistake is disputing the total without naming the line item. A reviewer cannot compare a general complaint against a ledger efficiently. Another is cancelling a payment before checking the consequence; a returned payment can trigger a second fee and leave the original issue unresolved. Read the due-date language first.
People also compare only dollar totals. If last month covered 28 days and this month covers 31, a daily service charge can rise even at the same rate. Dates shift. Compare days, units, rates, and credits. One number alone rarely explains the change.
Do not discard older statements after paying them. Keep at least 12 months of bills for recurring services, or longer if a contract, warranty, tax record, or dispute requires it. A PDF downloaded on June 3 may be the only copy after an online portal replaces prior records. Save it. Storage is cheap; reconstruction is not.
Finally, avoid phone-only disputes for errors with a deadline. Ask for a case number, then send a concise written notice through the stated channel. Include copies, not originals. The paper trail, annoyingly, often decides what can be reviewed later.
FAQ
What Should I Check First?
Check the billing period, total due, due date, and every line that differs from the prior statement. Then match unusual lines to receipts or notices.
Can A Pending Charge Be Disputed?
Usually wait until it posts unless the issuer says otherwise. A pending authorization may disappear or change within several days. Record it.
Why Is My First Bill Higher?
A first bill may combine a partial period, a full upcoming period, setup fees, or a deposit. Compare each date range.
How Long Should I Keep Bills?
For ongoing services, retain 12 months as a working record. Keep documents longer when they support a tax, contract, or unresolved claim.
What Makes A Dispute Strong?
Name the amount, date, and reason, then attach records that conflict with the charge. A focused request is easier to assess.
Author's Insight
Billing problems often look mysterious because a statement mixes several timelines in one total. Dates come first. Separating the service period, transaction date, payment-posting date, and due date reduces that confusion. The most useful review asks a narrow question for each line: what event created it, and which document supports it? That method also exposes cases where the amount is correct but the disclosure was too vague for a consumer to evaluate. Evidence guides judgment.
Key Takeaways
Audit a bill in layers: dates first, then rates and quantities, then fees, credits, and prior balance activity. A written record with the exact line item and attached evidence can turn a broad complaint into a reviewable request. Careful reading will not erase a disclosed charge, but it can uncover calculation errors, missed credits, or charges that lack a clear basis. Act before the stated deadline. Review every dated line before sending payment. Check dates, rates, and credits.